What Counts as Qualified Small Business Stock?
Section 1202 rewards a specific kind of stock. See the core tests – C-corp, original issuance, asset limit, active business, and holding period.
Section 1202 rewards a specific kind of stock. See the core tests – C-corp, original issuance, asset limit, active business, and holding period.
The 2025 law expanded Section 1202 – 50/75/100% exclusion tiers and a $15M cap. See how QSBS can exclude gain on a C-corp sale, and how it is lost.
Most owners start planning when an offer arrives – too late for the decisions that matter most. Five questions to answer while a sale is still hypothetical.
The sale price is not the number that matters – the after-tax result is. A CPA-led roadmap for the planning to do before the LOI and after the wire.
The exemption decides whether you owe estate tax – not whether your plan works. See what still needs attention even if your estate is under $15 million.
The estate tax exemption did not fall in 2026 – it rose to $15M per person, permanently. See what the new law means for your plan, and why review still matters.
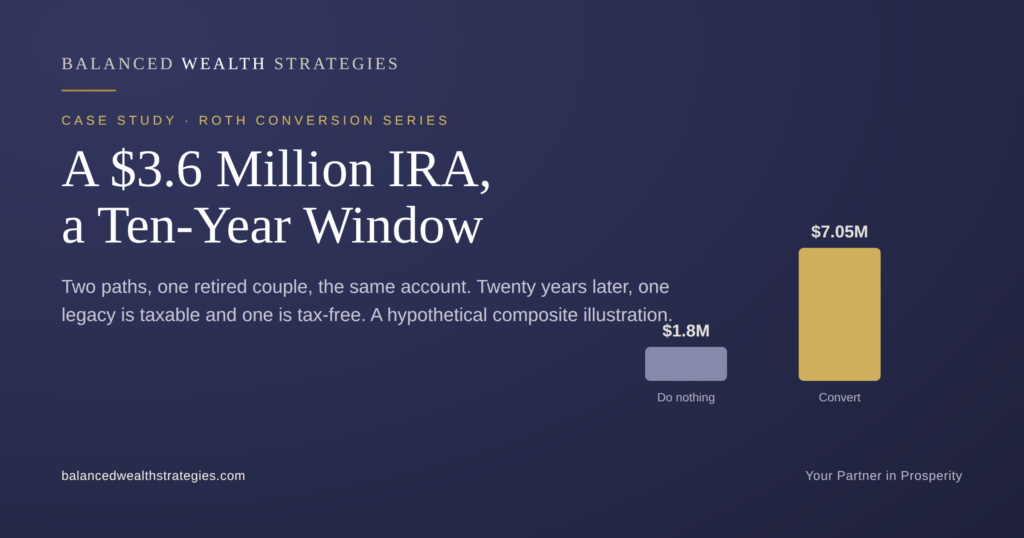
A hypothetical case study: how a measured Roth conversion turned a $3.6M IRA’s forced-distribution tax into a far larger tax-free legacy. Illustrative.
When a spouse dies, the survivor files as single and the brackets nearly halve. Part Three of a three-part series looks at how Roth conversions made while both spouses are alive can ease the survivor’s penalty.
Required minimum distributions can keep a large traditional IRA taxed for the rest of your life. Part One of a three-part series looks at how a measured Roth conversion strategy under 2026 tax law may reduce your own lifetime tax.